Many financial decisions look affordable only because the favourable outcome has already been silently built into the plan.
Perhaps the investment rises when expected. Perhaps a sale completes on time, an income stream starts, or a business outcome produces the cash you hoped for. But if bills, repayments or important goals only work when that sequence goes right, the commitment may be less affordable than it first appears.
The useful question is not whether an opportunity could work. It is whether the rest of your financial life still works if the outcome is late, smaller than hoped, or absent within the period that matters to you. This is a general planning framework, not individual financial, investment, tax, legal, debt or insurance advice.
A Good Outcome Is Not a Plan
A pressure test starts with a plausible unfavourable scenario. It does not ask you to predict a loss or assume failure. It asks whether your plan can absorb a setback without putting its most important parts under strain.
Start by separating two pools of money. One supports the obligations that keep your household finances and contractual commitments functioning: recurring bills, debt repayments, protection payments and dependent-related costs, as relevant to your situation. The other is money you can choose to allocate to an opportunity. “Essential obligations” is a planning term here, not a universal legal list; identify yours from your own budget.
Then consider your long-term goals. These are your own time-bound priorities that may need ongoing saving or investment contributions. A commitment can look attractive on its own while quietly requiring you to pause a goal, run down money needed elsewhere or depend on a future payment arriving exactly on schedule.
Liquidity belongs in this test. SEBI defines it as the ease with which an investment can be converted into cash without a significant impact on market value. In practical terms, eventual value is not the same as usable cash when an obligation falls due. An asset, project or expected payment may still be valuable later while being unable to help at the moment you need funds.
That distinction is not an argument against taking risk. Investment risks cannot be eliminated completely, and some commitments may be reasonable despite uncertainty. The point is to ensure that optimism is not doing the job of a cash-flow plan. Keep Emergency Fund Planning in view when deciding what must remain available rather than committed.
Run the Delayed Outcome Scenario
Check the fallback before relying on it
Map a delayed, reduced or absent outcome against bills, debt payments, protection payments, dependant-related costs and goal contributions. If borrowing is a possible fallback, assess repayment capacity and the applicable interest, processing, pre-payment and late-payment charges before signing.
Imagine you commit a substantial amount while expecting a financial benefit by a particular point: a return, sale, bonus, rental payment or business outcome. Keep the example deliberately generic. Now move the expected cash further out. Next, reduce it. Finally, remove it from the planning horizon altogether.
What changes first? Map the effects against the dates that cannot move easily: household bills, debt payments, protection payments, costs for dependants, planned purchases and existing savings contributions. A budget is useful here because it makes income, expenditure, debt repayment and goals visible in one place. This is the cash-flow question: what has to be paid before the hoped-for outcome arrives?
Timing can create pressure even when an underlying investment or project might eventually recover or succeed. In mutual funds and securities markets, for example, AMFI notes that trading volumes, settlement periods and transfer procedures can affect liquidity; tight conditions can also make selling more costly. That does not mean every commitment behaves like a mutual fund. It does show why a plan should not equate a future value with cash available today.
If your fallback is borrowing, do not assume it will be harmless or available on suitable terms. Before signing loan documents, SEBI advises borrowers to assess repayment capacity as well as applicable interest, processing, pre-payment and late-payment charges. Keep Cash Flow Planning in the picture: the question is not merely where money might come from, but what that source would do to the rest of the plan.
Find the Assumptions Doing the Work
Fragility often comes from a stack of reasonable-sounding assumptions rather than one obviously reckless choice. The plan may assume your income continues, expenses stay stable, cash remains accessible, a buyer appears when wanted, credit is available if needed, you will not need to sell early and a setback will be recoverable.
Any one of these may prove true. The concern is that several can become less dependable at the same time. A higher expense can arrive while income is disrupted, or cash can be needed at the same point an investment is less convenient to sell. You do not need to forecast that combination to acknowledge that it would change your room to manoeuvre.
This exposes a difference between market risk and plan risk. You may be comfortable seeing an investment decline in value, especially over a longer horizon. But you may not be comfortable with the cash-flow consequence if that decline means an essential payment, debt-reduction plan or meaningful goal contribution has to be interrupted.
Diversification can reduce some investment risk, but it does not guarantee against loss or make every commitment suitable for every horizon. SEBI’s educational guidance connects allocation with goals, risk tolerance and time horizon. That is why the appeal of an opportunity should be assessed separately from the strength of the plan supporting it. Investment Risk Tolerance is about more than your reaction to a price move; it also concerns your capacity to live with the knock-on effects.
Use Four Questions Before Committing
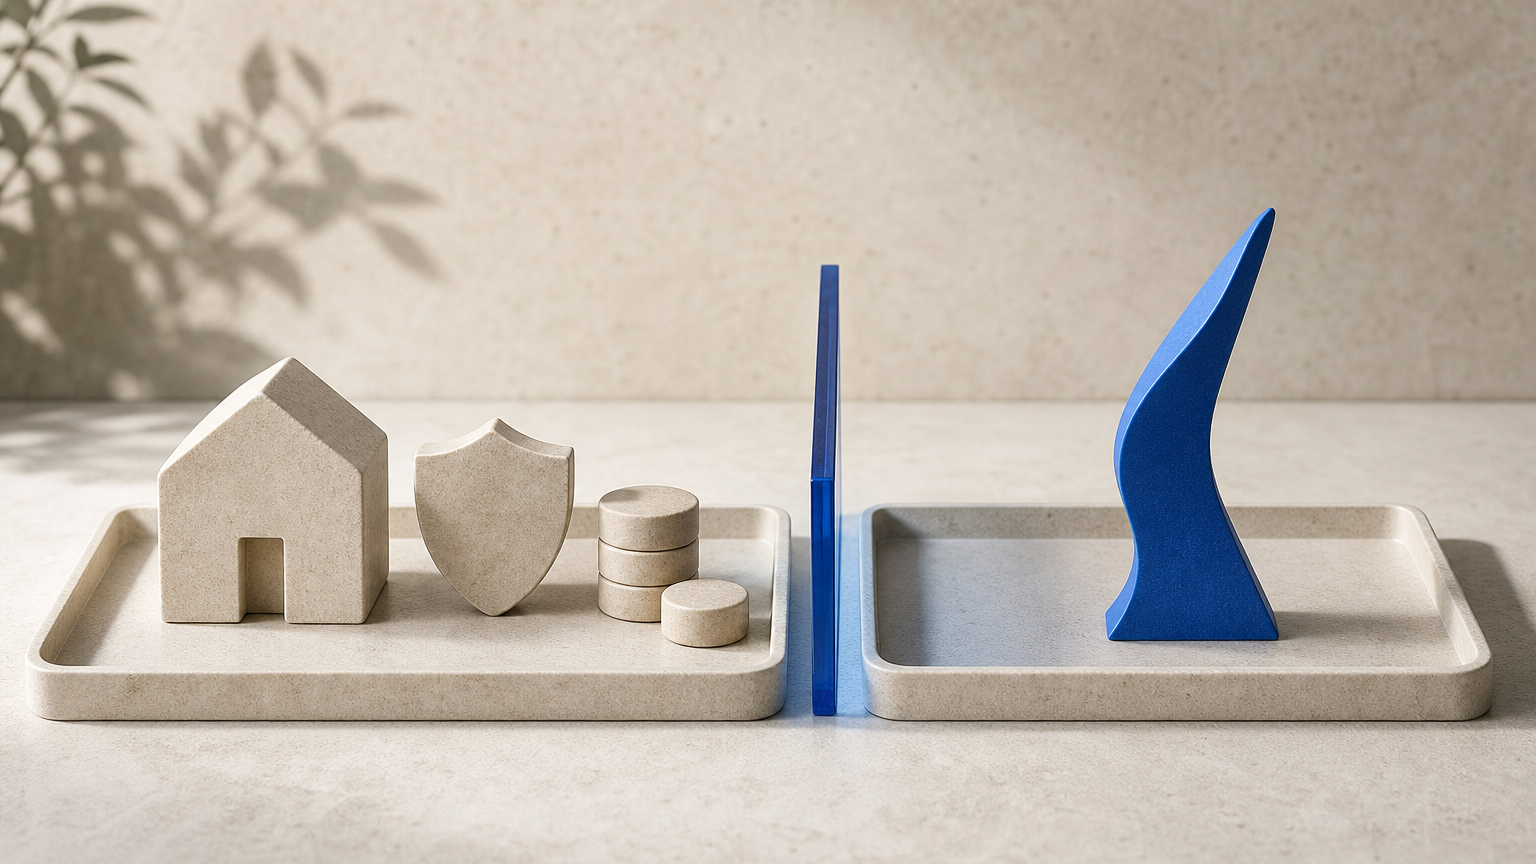
Two ways to frame the decision
Return-led decision
- Centres on the expected payoff.
- Relies heavily on the expected timing of the outcome.
- Treats eventual value as the main measure of affordability.
Resilience-led decision
- Considers safety, return and liquidity together.
- Identifies essential obligations and fallback cash sources.
- Makes goal trade-offs explicit before committing.
- Tests assumptions, including those least under the reader’s control.
This is an editorial decision lens, not an official classification or a universal suitability rule.
Write down the answers before funds are tied up. The act of documenting them makes dependencies easier to spot and gives you something concrete to revisit if terms, timing or your household position changes.
-
If the expected outcome is worth less or never arrives, which essential obligations would be affected? Name the payments and responsibilities rather than answering in generalities. This helps distinguish inconvenience from a disruption to core commitments.
-
If access to the committed money takes longer than expected, what cash source covers obligations without borrowing on terms that would worsen the position or selling at an unfavourable time? Check the actual terms of any potential borrowing or withdrawal route rather than assuming it is available.
-
What long-term goal contributions, debt-reduction plans or protection needs would be paused or reduced—and is that trade-off intentional? A deliberate, documented trade-off is different from discovering it only after cash is constrained.
-
What assumptions must all hold for the commitment to feel affordable, and which one is least under your control? This turns a vague sense of confidence into a list that can be challenged.
There is no universal pass mark. Instead, set a personal downside boundary: identify what must remain protected if the favourable case does not arrive. If the answers show that core obligations or deliberately chosen priorities would not remain viable, consider reducing the amount, changing the terms, delaying the decision or preserving more liquidity. Financial Goal Setting can help frame the trade-off against the goals you have already chosen.
Choose Flexibility Over Perfect Forecasts
Financial confidence is not the ability to call the favourable outcome correctly. It is having options when reality differs from the plan.
A commitment may still be worth considering when you can explain how essential obligations and chosen long-term priorities remain protected under a plausible setback. Uncertainty alone does not make an opportunity unsuitable. What matters is whether its downside effects are understood and manageable within your circumstances.
The appropriate level of flexibility depends on income stability, dependants, debt, time horizon and the commitment’s actual terms. Access to credit, charges, withdrawal conditions, taxes, penalties and contractual remedies can vary by product, provider, contract and jurisdiction, so check current applicable terms before acting.
For a complex, high-stakes, tax-sensitive or debt-related decision, seek appropriately qualified professional guidance. For personalised securities-related investment advice in India, consider checking whether an adviser is SEBI-registered. Other matters—such as tax, legal, property, insurance or business questions—may need a different qualified professional.
Before committing, write down the unfavourable scenario you could realistically absorb and use it to test what must remain protected. Financial Planning Basics begins with that discipline: preserving room to respond, rather than requiring a perfect forecast.
Sources & Further Reading
- Securities Market Investment: How to Manage Investment Risks | SEBI Investor
- Investments: Factors to Consider Before Investing | SEBI Investor
- Financial Education – Part A
- Personal Finance & Investment: Money matters: Financial Goals and Budgeting | SEBI Investor
- Risks in Mutual Funds | AMFI
- Financial Education Booklet | SEBI Investor
- Personal Finance & Investment: Think Before You Borrow Money | SEBI Investor
- Master Circular for Investment Advisers | SEBI